
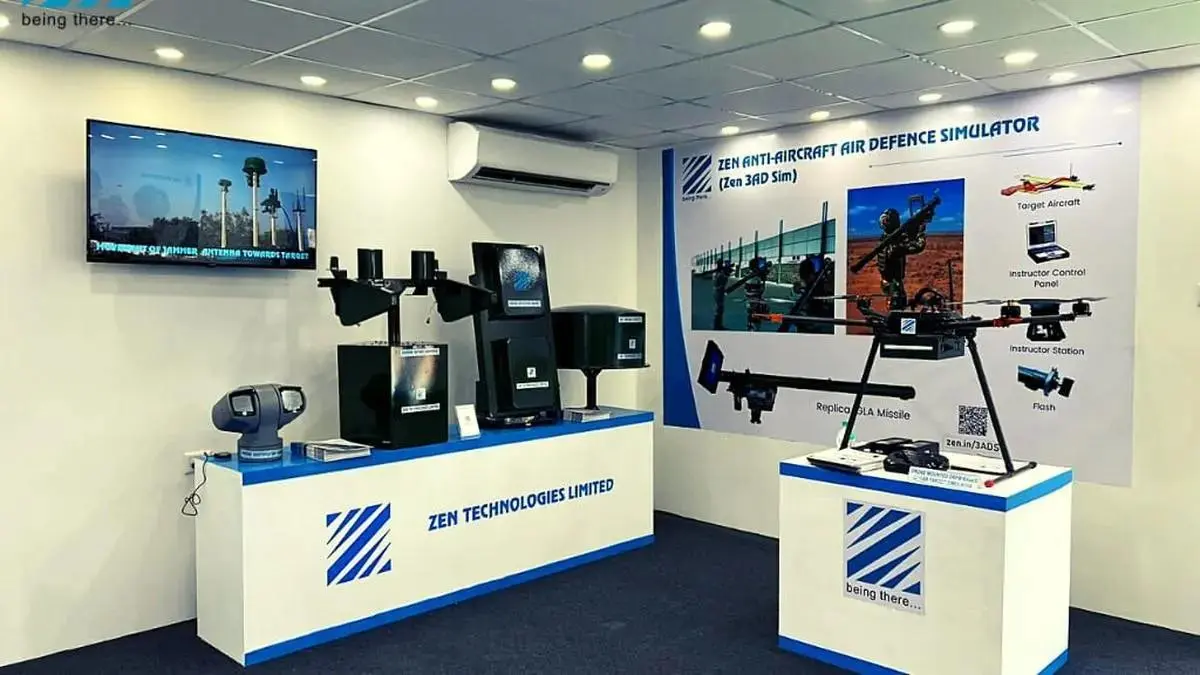

Zen’s indigenous CUAS capabilities across radars, detection systems, jammers and command-and-control position it favourably
Target: ₹2,150
CMP: ₹1,715
Zen Technologies delivered its highest-ever quarterly revenue of ₹345.1 crore, up 98.8 per cent year on year, with operational EBITDA/PAT growing strongly. EBITDA margin stood at 38.2 per cent, broadly in line with guidance of mid-30s. The company secured order inflows of ₹482 crore during the quarter, taking the consolidated order-book to ₹1,376 crore (2.0x of FY26 revenue). We believe the improvement in execution, coupled with a growing order-book, provides a strong revenue base for H2FY27.
We expect the CUAS segment to remain a key medium-term growth driver, with procurement progressing through the fast track route. FTP-related RFPs could begin in the coming weeks, with initial awards likely in Q4FY27, although delays may extend into FY28. Zen’s indigenous CUAS capabilities across radars, detection systems, jammers and command-and-control position it favourably. Additionally, ₹400 crore of simulator opportunities and its expanding naval simulation portfolio offer further order and export potential. We expect conversion of these opportunities to strengthen order-book visibility and support growth.
We have revised our FY27E and FY28E financial estimates to reflect the improved revenue trajectory.
Considering the company’s medium-term growth potential and expanding tech portfolio, we have increased our target valuation multiple to 35x (from 30x). We upgrade our rating to Buy (from Add) and raise our target price to ₹2,150 (earlier ₹1,850), valuing the stock at 35x the average FY28-29E EPS.
Published on November 3, 2026